
Organisations frequently misinterpret top-line revenue as an accurate indicator of actual profit contribution, obscuring the real profit drivers across their complex operations. Without precise contribution margin insights, strategic decisions regarding product lines, customer segments, and sales channels often rely on incomplete data, leading to suboptimal investment and operational inefficiencies. This article delves into the mechanics of contribution margin analysis, its critical role in identifying true profit centers, and how advanced analytics facilitate robust decision-making by prioritizing high-value segments.
Contribution margin represents the revenue available to cover fixed costs after accounting for variable costs associated with production or service delivery. It provides a clearer picture of an item’s profitability than gross margin, which often includes allocated fixed overheads, thus distorting the true incremental profit each product, customer, or channel brings.
The Misconception of Top-Line Revenue
Many enterprises focus disproportionately on top-line revenue growth, overlooking the associated costs that erode actual profitability. A high-revenue product might command significant variable costs (raw materials, commissions, delivery), resulting in a low contribution margin. This scenario creates an illusion of success while draining resources that could be better allocated to segments with higher profit contribution.
Relying solely on revenue size prevents a granular understanding of where the enterprise truly generates value. This strategic blind spot can lead to investments in underperforming areas, hindering overall financial performance and competitive positioning. Identifying true profit drivers requires moving beyond traditional revenue metrics.
Understanding Contribution Margin Mechanics
Contribution margin is calculated as Sales Revenue minus Variable Costs. This metric is fundamental for activity-based costing and profitability analysis. Variable costs fluctuate directly with production volume or service delivery, including direct materials, direct labor, and sales commissions. Fixed costs, such as rent, salaries, and depreciation, remain constant regardless of activity levels.
By isolating the contribution margin, organisations can assess the inherent profitability of each unit of sale, whether it’s a product, a customer order, or a specific channel transaction. This distinct view supports critical decisions on pricing, product mix, and market segment targeting, allowing finance and commercial teams to pinpoint areas for optimization and strategic divestment.
Identifying Real Profit Drivers: Product, Customer, Channel
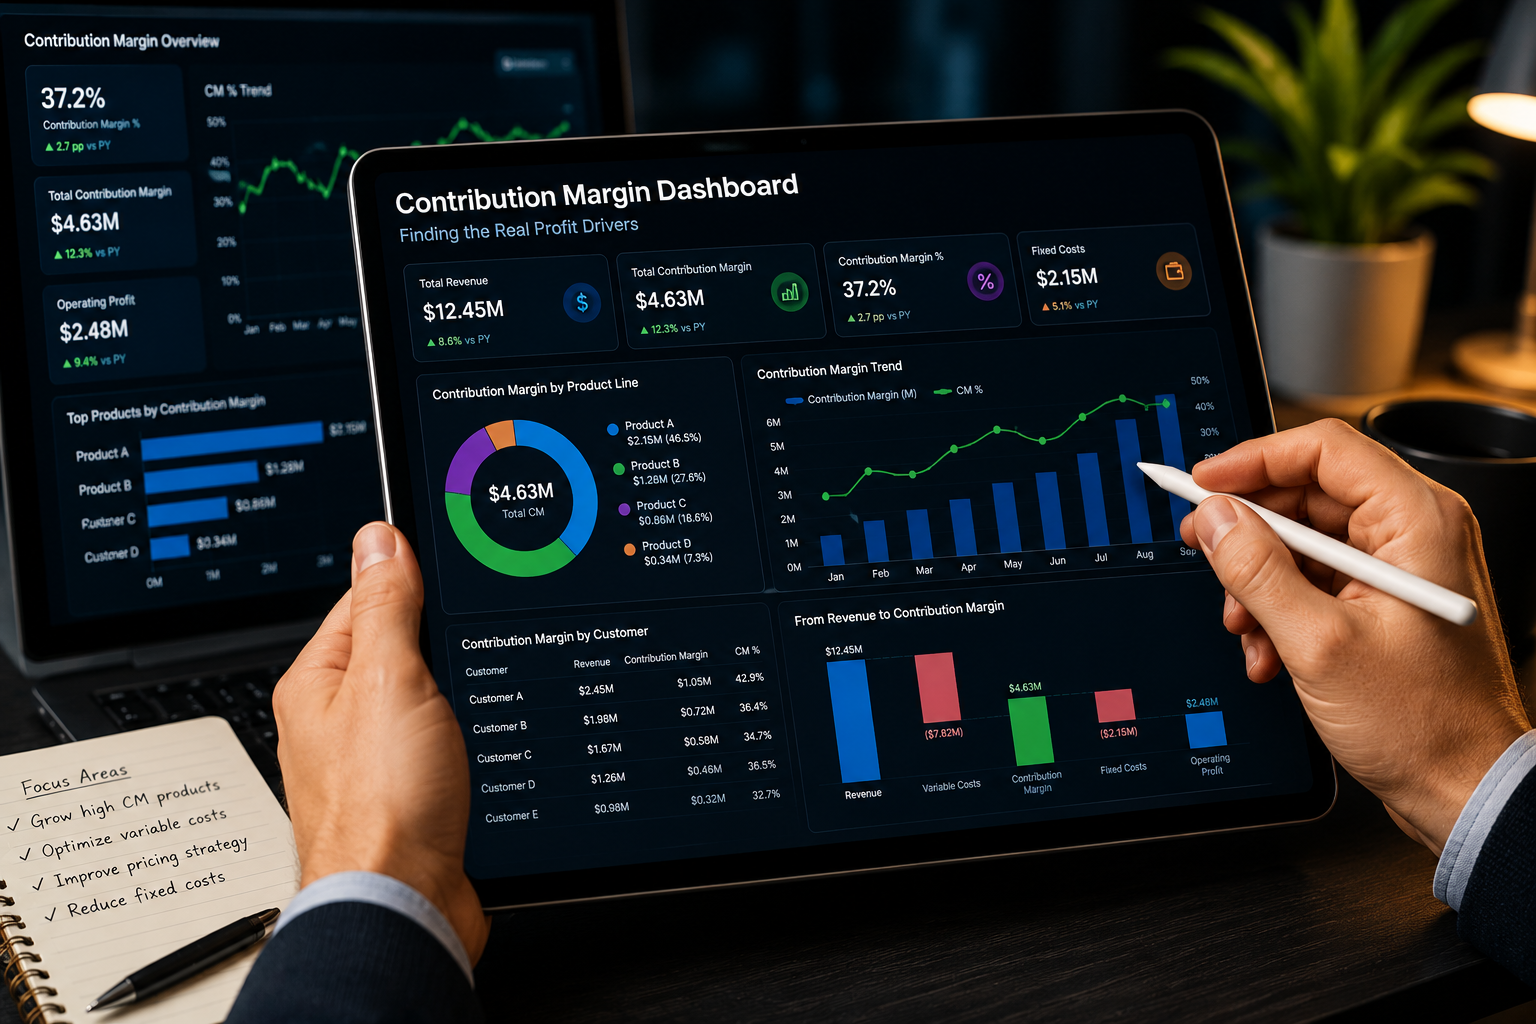
A sophisticated contribution margin dashboard empowers leadership to rank products, customers, and sales channels by their actual profitability. This deep-dive analysis reveals that not all revenue streams are equally valuable. A customer with high annual spend but demanding extensive, costly services may have a lower contribution margin than a smaller, self-sufficient client.
Similarly, a product generating significant sales volume but requiring frequent customisations or complex logistics might contribute less profit than a niche item with streamlined operations. By quantifying these differences, enterprises can strategically reallocate resources, focus sales efforts, and refine operational processes towards segments that demonstrably drive higher profit contribution.
High-Performance Dashboard Layout for Profitability Analysis
An effective contribution margin dashboard integrates visual clarity with analytical depth. Key performance indicators (KPIs) like contribution margin percentage by product line, customer segment, and sales channel should be prominently displayed. Interactive visualisations enable drill-down capabilities from aggregate views to individual transactions, revealing the underlying cost structures.
Dynamic filters allow users to slice data by region, time period, sales representative, or product category. This facilitates rapid identification of anomalies or emerging trends in profitability. Visual cues, such as heatmaps or variance charts, immediately highlight underperforming segments requiring strategic intervention, ensuring insights are actionable and timely.
Traditional vs Modern Profitability Dashboards
Traditional profitability reporting typically involves static spreadsheets or basic BI tools, offering limited drill-down functionality and requiring significant manual effort for data aggregation. These reports often present historical data without dynamic analysis capabilities, making proactive decision-making challenging.
Modern contribution margin dashboards, conversely, are built on integrated data platforms, providing real-time data, interactive visualisations, and predictive analytics. They enable scenario modelling to assess the impact of pricing changes or cost reductions, moving from reactive reporting to proactive strategic planning and granular profitability management.
Who Should Use This System
This system is crucial for a broad spectrum of enterprise stakeholders. Finance teams gain an unparalleled view of granular profitability across all dimensions. Commercial and Sales leadership can refine strategies to target high-value customers and products. Operations can identify cost inefficiencies tied to specific offerings or delivery models. Ultimately, executive leadership relies on these insights to make informed decisions on resource allocation, investment priorities, and strategic growth initiatives.
Key Architectural Components
Implementing a robust contribution margin dashboard necessitates a scalable and integrated architecture. The foundation includes a secure data ingestion layer, capable of integrating diverse data sources from ERP systems (e.g., SAP, Oracle), CRM platforms, and various operational databases. This feeds into a unified data lake or data warehouse for raw and processed data storage.
A high-performance processing engine handles data transformation, normalisation, and the application of complex contribution margin models. Analytical services provide predictive and prescriptive insights, identifying patterns and forecasting profitability trends. The presentation layer, comprising advanced dashboarding tools, ensures data accessibility and interactive exploration for all stakeholders, supported by robust security and access controls.
Key Deployment Challenges
Deployment of such a system often encounters several challenges. Data fragmentation across disparate legacy systems can complicate aggregation and ensure data quality. Defining accurate variable costs, especially in complex manufacturing or service environments, requires meticulous data mapping and validation. Integrating with existing enterprise architecture and ensuring seamless data flow demands careful planning and execution.
Another significant hurdle is user adoption, requiring comprehensive training and change management strategies to shift from traditional reporting methods. Performance scalability for large datasets and ensuring compliance with data governance and audit readiness standards are also critical considerations throughout the deployment lifecycle.
| Capability | Traditional | AI System |
| Data Aggregation | Manual, disparate sources, prone to errors, slow. | Automated, unified data model, real-time integration. |
| Data Lineage Tracking | Limited, often undocumented, difficult to audit. | End-to-end traceability, automated audit trails. |
| Multi-Entity Consolidation | Labor-intensive, reconciliation challenges, delayed. | Automated, rule-based, rapid and accurate consolidation. |
| Audit Readiness | Fragmented data, manual documentation, long cycles. | Integrated audit logs, verifiable data points, accelerated compliance. |
| Scenario Modelling | Static spreadsheets, limited variables, hypothetical. | Dynamic, multi-variable, predictive analytics, actionable insights. |
The stark contrast between traditional and AI-powered systems highlights a fundamental shift from data collection and reconciliation to actionable intelligence. AI-driven platforms move beyond merely presenting data; they actively analyse, reconcile, and model outcomes, delivering a level of foresight and operational agility unattainable with legacy approaches. This significantly reduces manual effort, enhances data integrity, and accelerates strategic decision-making cycles.
How NumeriQu Enables This Capability
NumeriQu provides a unified financial intelligence platform engineered to address the complexities of contribution margin analysis at an enterprise scale. It seamlessly ingests diverse financial and operational data from core ERP systems like SAP and Oracle, alongside CRM platforms and other bespoke operational systems. Through advanced AI-driven reconciliation and anomaly detection, Numeriqu cleanses, validates, and standardises data, creating a single source of truth for profitability metrics. Its processing engine applies granular variable cost models to generate precise contribution margins across products, customers, and channels, automatically ranking segments by profitability. The platform then presents these insights through interactive, drill-down dashboards, offering both high-level summaries and detailed transaction views. This approach goes beyond generic BI tools by providing pre-built financial intelligence models and automation specifically designed for profit analytics, offering a deeper, more contextual understanding than standard ERP reporting modules.
Operational Scenarios
Scenario 1: Optimizing Product Portfolio
Problem: A large industrial manufacturer observed declining overall profit margins despite stable revenue. It lacked granular visibility into individual product line profitability beyond gross margin.
Implementation: The enterprise deployed a contribution margin dashboard, integrating cost data from its ERP and operational systems. The dashboard automatically segmented products by variable costs, sales volume, and actual profit contribution, ranking them accordingly.
Measurable Outcome: Within six months, the manufacturer identified two high-revenue product lines that consistently generated low contribution margins due to high material costs and extensive post-sales support. Strategic adjustments, including targeted price increases and process automation for these lines, led to an 18% uplift in average product contribution margin and a 10% overall profit margin improvement.
Scenario 2: Refining Customer Segmentation
Problem: A B2B service provider struggled with resource allocation, with sales teams often prioritising large accounts that consumed disproportionate service hours without corresponding profitability.
Implementation: A contribution margin analysis system was implemented to calculate the profit contribution of each customer, factoring in direct service costs, commissions, and specific project expenses. The dashboard visualised customer segments by profitability tiers.
Measurable Outcome: The analysis revealed that 20% of the largest customers contributed only 10% of the total profit, while a segment of medium-sized customers delivered 40% of the profit with lower support overheads. This insight enabled the sales team to re-focus efforts, renegotiate service level agreements for underperforming large accounts, and optimise sales strategies, resulting in a 25% increase in customer profitability within the top quartile.
Before and After: The Impact on Financial Operations
Before implementing an advanced contribution margin dashboard, financial teams typically spent weeks manually consolidating data from disparate sources, reconciling discrepancies, and generating static reports. This process was prone to errors, delayed critical insights, and limited proactive decision-making.
With a modern system, reporting speed is accelerated by over 70%, with real-time dashboards providing immediate access to current profitability metrics. Error reduction reaches up to 40% through automated data validation and AI-driven reconciliation. Decision-making improvement is profound, as leadership can now proactively identify and address profit leakages, leading to a 20-40% efficiency gain in resource allocation and strategic planning.
Technology Maturity and Enterprise Adoption Timeline
The maturity of financial analytics platforms has progressed significantly, enabling rapid deployment of contribution margin dashboards. Initial adoption can focus on quick wins by integrating core revenue and variable cost data, providing foundational insights within 3-6 months. A phased rollout allows for iterative refinement of data models and user interfaces, building confidence and fostering wider organisational adoption.
Full enterprise integration, including advanced scenario modelling, predictive analytics, and integration with operational planning systems, typically spans 12-18 months. This timeline includes establishing robust data governance frameworks and comprehensive training programs to ensure sustained utilisation and maximise the strategic value derived from the platform.
Key Takeaways
- Contribution margin reveals true profit drivers, moving beyond top-line revenue metrics.
- Granular analysis across products, customers, and channels enables strategic resource reallocation.
- Modern dashboards provide real-time, interactive insights for proactive decision-making.
- Integrated architecture and robust data governance are critical for successful implementation.
- AI-powered systems offer significant advantages over traditional reporting in speed, accuracy, and foresight.
Frequently Asked Questions
What is the primary difference between gross margin and contribution margin?
Gross margin includes all costs of goods sold, which can contain allocated fixed overheads. Contribution margin, however, specifically subtracts only variable costs from revenue, providing a clearer view of an item’s incremental profitability and its contribution to covering fixed costs.
Why is granular variable cost data essential for a contribution margin dashboard?
Accurate, granular variable cost data is critical because it directly impacts the precision of contribution margin calculations. Without it, the dashboard cannot reliably identify which products, customers, or channels are truly contributing to profit, leading to flawed strategic decisions.
Can a contribution margin dashboard help with pricing strategies?
Yes, absolutely. By understanding the contribution margin of each product or service, businesses can set optimal pricing strategies. It helps determine the lowest price point they can accept while still covering variable costs and contributing to fixed costs, avoiding loss-making sales.
What kind of data sources are typically integrated for this analysis?
Typical data sources include ERP systems for sales revenue, cost of goods sold, and general ledger data. CRM systems provide customer-specific data. Additionally, operational systems may feed in variable manufacturing costs, logistics expenses, and direct labor costs.
How does this system differ from standard financial reporting in an ERP?
While ERPs offer financial reports, they often lack the detailed, dynamic, and cross-dimensional contribution margin analysis capabilities required for strategic profit optimisation. Dedicated systems are built for complex data modelling, real-time analytics, and interactive dashboards focused specifically on profit drivers.
If your organisation is evaluating scalable operating models, a focused contribution margin dashboard approach may warrant a structured review across cost, governance, and long-term operational resilience. To explore what that could look like in practice, contact NumeriQu for a consultative discussion.